If you already have an active VA loan, can you still use your VA benefit to buy a home in Chula Vista, San Diego in 2026?
Yes, you can buy again in Chula Vista using your VA benefit, but you need to either restore your full entitlement by paying off your existing VA loan or use your remaining partial entitlement with a possible down payment.
Why This Matters for San Diego Veterans Right Now
Here’s the situation I see regularly. You used your VA loan a few years ago, maybe for a condo in Mira Mesa or a townhome near base. Now you’re ready to move up, and Chula Vista is calling. But your first VA loan is still active, and you’re not sure where that leaves you.
You’re not alone. With 16 years of experience as an Associate Broker in San Diego and a specialty in VA loans, I’ve walked dozens of veterans through this exact scenario. The good news: you have options. The tricky part: the path you choose depends on what you want to do with your current property.
Chula Vista’s median home price is sitting around $800,000 right now, essentially flat year over year. That stability, combined with San Diego County’s 2026 conforming loan limit of $1,104,000, gives you some real flexibility. But a cloudy mind can’t make decisions, so let me lay out your options clearly.
Understanding Your VA Entitlement When Your First Loan Is Still Active in San Diego
First, let’s get grounded in the numbers. In 2026, your VA entitlement breaks down like this:
- Basic entitlement: $36,000 (covers loans up to $144,000)
- Bonus entitlement: $191,637 (for loans above $144,000)
- Total maximum entitlement: $227,637
If you have full entitlement, you can purchase at any price with zero down, as long as you qualify with your lender. That’s thanks to the Blue Water Navy Vietnam Veterans Act of 2019, which eliminated loan limits for veterans with full entitlement.
But here’s the catch. If your first VA loan is still active, you don’t have full entitlement. You have partial entitlement, which means the portion of your guarantee tied up in that first loan reduces what’s available for your next purchase.
What does that actually mean for your wallet? It means you may need a down payment on your Chula Vista purchase, or you may need to take steps to restore your full entitlement first. Let’s walk through each path.
Four Ways to Restore or Work Around Your VA Entitlement in Chula Vista
Path 1: Sell Your Current Home and Pay Off the VA Loan
This is the cleanest route. You sell the property tied to your existing VA loan, pay it off in full, and submit VA Form 26-1880 with proof of payoff and your HUD-1 settlement statement. The VA restores your full entitlement, and you’re free to purchase in Chula Vista with zero down.
I recently worked with a Navy family stationed in San Diego who owned a condo near Sorrento Valley. They wanted to move to Otay Ranch in Chula Vista for the schools and extra square footage. Once they sold the condo and the VA processed their 26-1880, their full entitlement was restored in about a week. They closed on a four-bedroom in the 91913 ZIP code with zero down.
Processing time for VA Form 26-1880 is typically 5 to 10 business days through the VA Regional Loan Center. Lenders with WebLGY portal access can pull a refreshed Certificate of Eligibility in under 48 hours. And submitting the form costs nothing.
Path 2: One-Time Restoration (Keep the Property, Pay Off the Loan)
This one surprises a lot of veterans. If you pay off your VA loan but keep the property, the VA offers a one-time restoration of your entitlement. This is huge if you want to turn your current home into a rental while buying your next primary residence in Chula Vista.
The critical requirement: you must pay off the VA loan first. That usually means refinancing into a conventional loan. Once the VA loan balance is zero, you file for the one-time restoration.
Here’s what I tell my clients: this is a powerful tool, but it’s a one-and-done benefit. You get one shot at this in your lifetime. If you think you might want to use it later for a different property, think carefully before pulling the trigger now.
Path 3: VA Loan Assumption by Another Eligible Veteran
If you’re selling to another qualified veteran, they can assume your VA loan through a Substitution of Entitlement. When this happens, your entitlement is released and restored. It’s less common, but I’ve seen it work well in San Diego’s military-heavy market.
Path 4: Use Your Remaining Partial Entitlement
You don’t have to restore anything if you’re comfortable making a down payment. Your remaining entitlement, combined with a down payment, just needs to equal at least 25% of the purchase price for most lenders.
So if you’re looking at a $800,000 home in Chula Vista’s Eastlake or Rolling Hills Ranch neighborhoods, you’d calculate how much entitlement is still available and bridge the gap with cash. For some buyers, this is actually the fastest path because there’s no waiting for restoration paperwork.
What Chula Vista Looks Like for VA Buyers in 2026
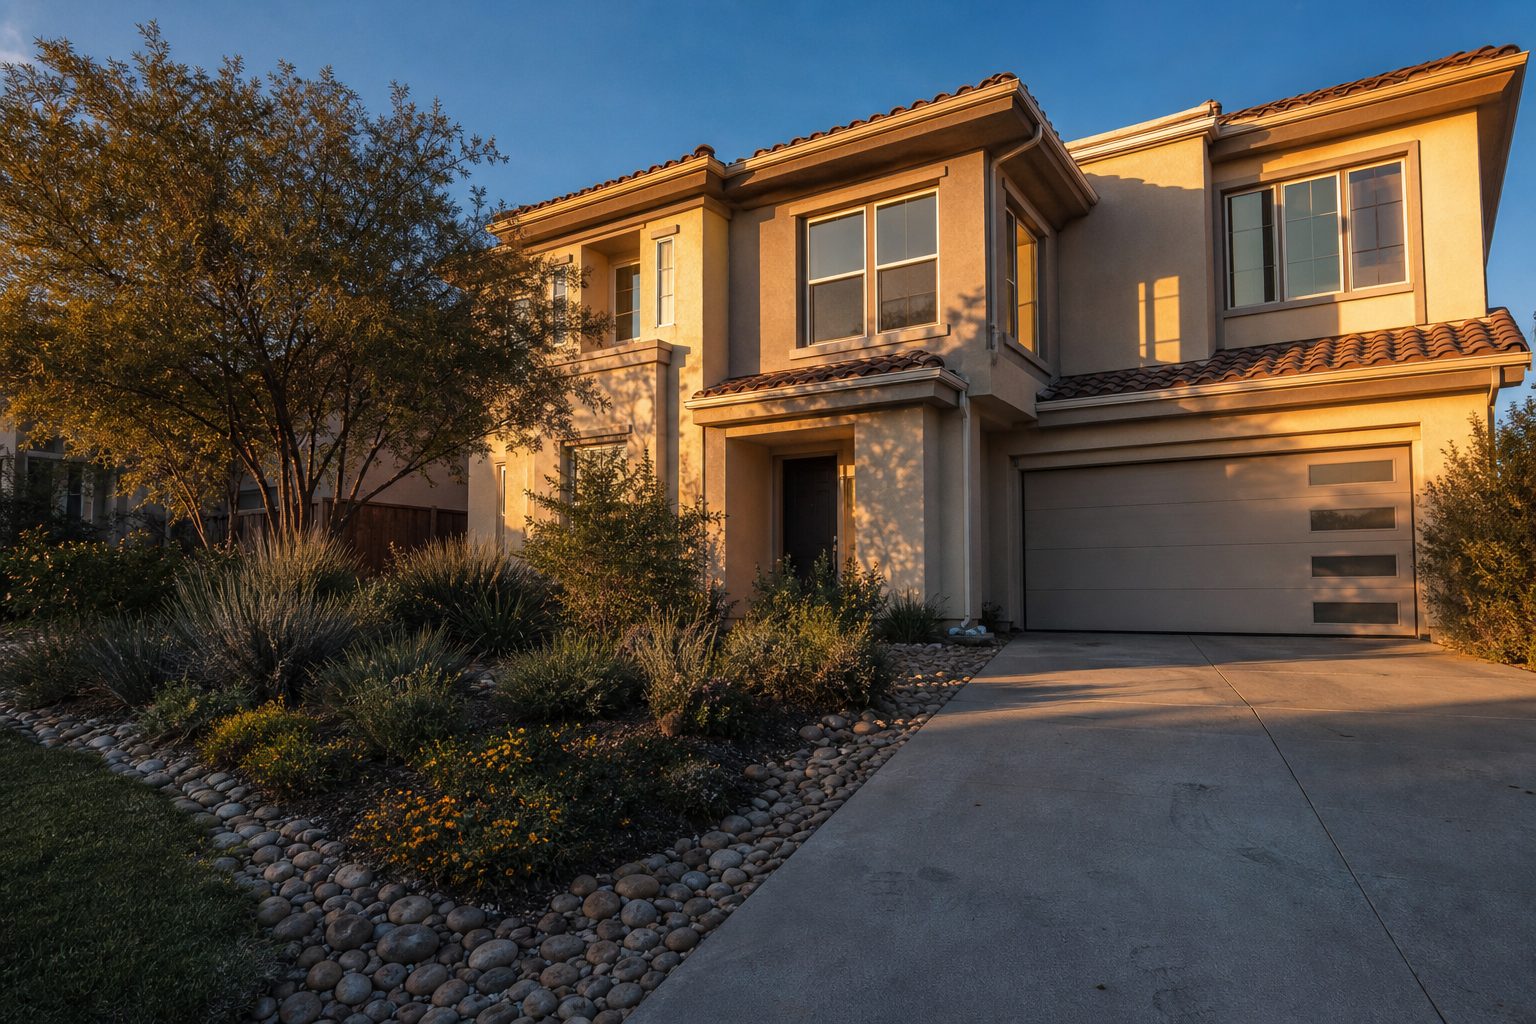
Why do so many veterans land in Chula Vista? The combination of price, proximity, and lifestyle is hard to beat anywhere else in San Diego County.
Consider the numbers. San Diego County’s detached single-family median is $1,099,500. Chula Vista’s median is around $800,000. That’s a significant difference, and it stretches your buying power considerably, especially with VA financing.
Here’s what different Chula Vista neighborhoods look like:
- 91913 (Otay Ranch, Eastlake, Windingwalk): Higher-end detached homes, popular with families and military buyers. Expect median prices in the upper range.
- 91914 (Rolling Hills Ranch, Eastlake Vistas): Similar appeal, with well-maintained master-planned communities.
- 91911 (Southwest Chula Vista): One of the more affordable entry points for both detached and attached housing. Great option if you’re stretching partial entitlement.
Detached inventory in Chula Vista is limited across all five ZIP codes, and well-priced homes are moving in 20 to 30 days. Having closed over 275 transactions in San Diego County, I can tell you that VA offers are competitive here when they’re structured correctly with strong pre-approval and clean documentation.
VA Funding Fee Considerations for Your Chula Vista Purchase
Since this would be a subsequent use of your VA loan benefit, your funding fee is 3.3% with zero down, compared to the 2.15% first-use rate. On a $800,000 purchase, that’s $26,400 rolled into your loan.
However, the funding fee is waived entirely if you:
- Receive VA disability compensation at 10% or higher
- Are a surviving spouse of a veteran who died in service or from a service-connected disability
- Received a Purple Heart
I always recommend that my clients confirm their exemption status before running the numbers. One couple I worked with didn’t realize their 10% disability rating waived the fee completely, saving them over $25,000 on their Chula Vista purchase.
Step-by-Step: Your Action Plan for Buying in Chula Vista With VA Entitlement
Here’s the sequence I walk my clients through, and with 180 five-star reviews and a top 1% ranking among San Diego real estate agents, this process has been refined over years of real transactions:
- Step 1: Pull your current Certificate of Eligibility to see exactly how much entitlement is available versus in use. Check VA loan eligibility requirements to ensure you’re current on requirements.
- Step 2: Decide your path. Are you selling, refinancing, or using partial entitlement?
- Step 3: If restoring, gather your loan payoff statement and closing documents, then submit VA Form 26-1880.
- Step 4: Get pre-approved with a VA-experienced lender who understands San Diego County’s conforming limit of $1,104,000.
- Step 5: Connect with a real estate broker in San Diego who has specific experience with VA loan timelines, partial entitlement scenarios, and Chula Vista’s neighborhood dynamics.
Frequently Asked Questions
Can I have two VA loans at the same time in San Diego?
Yes. If you have remaining entitlement, you can use it for a second VA loan. You’ll need to occupy the new home as your primary residence. The key factor is whether your remaining entitlement covers 25% of the new purchase price, or whether you’ll need a down payment to make up the difference.
How long does it take to restore VA entitlement after selling my home?
The VA Regional Loan Center typically processes Form 26-1880 in 5 to 10 business days. Lenders with direct portal access can sometimes pull a refreshed Certificate of Eligibility in under 48 hours. There’s no filing fee for restoration.
Do I have to sell my current home to restore entitlement?
Not necessarily. The one-time restoration allows you to keep the property as long as the VA loan is paid off, typically through refinancing into a conventional loan. This is a one-time, lifetime benefit, so use it strategically.
What is the VA loan limit in San Diego County for 2026?
The 2026 conforming loan limit for San Diego County is $1,104,000 for a single-family property. Check current VA loan limits to see how much you can borrow. Veterans with full entitlement have no loan limit and can purchase above this with zero down if they qualify. Veterans with partial entitlement may face limits based on available entitlement.
Is Chula Vista a good place for veterans to buy in San Diego?
Chula Vista is one of the most popular destinations for military-connected buyers in San Diego. Its proximity to Naval Base San Diego, combined with median prices around $800,000 (well below the county-wide detached median of $1,099,500), makes it a strong value play. The Otay Ranch and Eastlake areas are especially popular with military families.
What’s the VA funding fee for a second VA loan?
For subsequent use with zero down, the funding fee is 3.3% of the loan amount. This can be rolled into the loan. Veterans with a service-connected disability rating of 10% or higher are exempt from the funding fee entirely.
Can another veteran assume my VA loan?
Yes. If an eligible veteran assumes your loan through a Substitution of Entitlement, your entitlement can be released and restored. This requires lender and VA approval but can be a clean solution when selling to another veteran.
What happens if I use partial entitlement and the home costs more than my coverage?
Your lender will require a down payment to cover the gap between your remaining entitlement guarantee and 25% of the purchase price. For example, on an $800,000 home, you need $200,000 in combined entitlement and down payment. Whatever your remaining entitlement doesn’t cover, you bridge with cash.
Should I refinance my first VA loan to conventional before buying in Chula Vista?
If you want to keep your current property and restore entitlement, yes. Refinancing to conventional pays off the VA loan, which is the prerequisite for the one-time restoration. I always recommend running the numbers on the conventional rate versus keeping the VA rate to make sure the math works in your favor.
How do I find a real estate agent in San Diego who understands VA loans?
Look for an agent or broker with documented VA loan experience, not just someone who says they work with veterans. With 16 years specializing in VA transactions across San Diego County and an Associate Broker designation (DRE# 01509668), I bring an extra layer of contract review and negotiation expertise to every VA purchase.
The Bottom Line
Restoring your VA loan entitlement to buy in Chula Vista in 2026 is absolutely doable, but the right path depends on your specific situation. Whether you sell, refinance, or work with partial entitlement, the key is getting clear information before making any moves. A cloudy mind can’t make decisions, and this is too important a decision to navigate on assumptions.
If you’re a veteran or active-duty service member thinking about Chula Vista or anywhere else in San Diego County, I’d welcome the chance to map out your options. I’m Scott Cheng, Associate Broker at REAL Brokerage, and you can reach me at 858-405-0002. I also provide a complimentary attorney review of contracts and disclosures for every buyer I work with, covered by me, even if escrow cancels. Let’s build a plan that makes sense for your situation.